
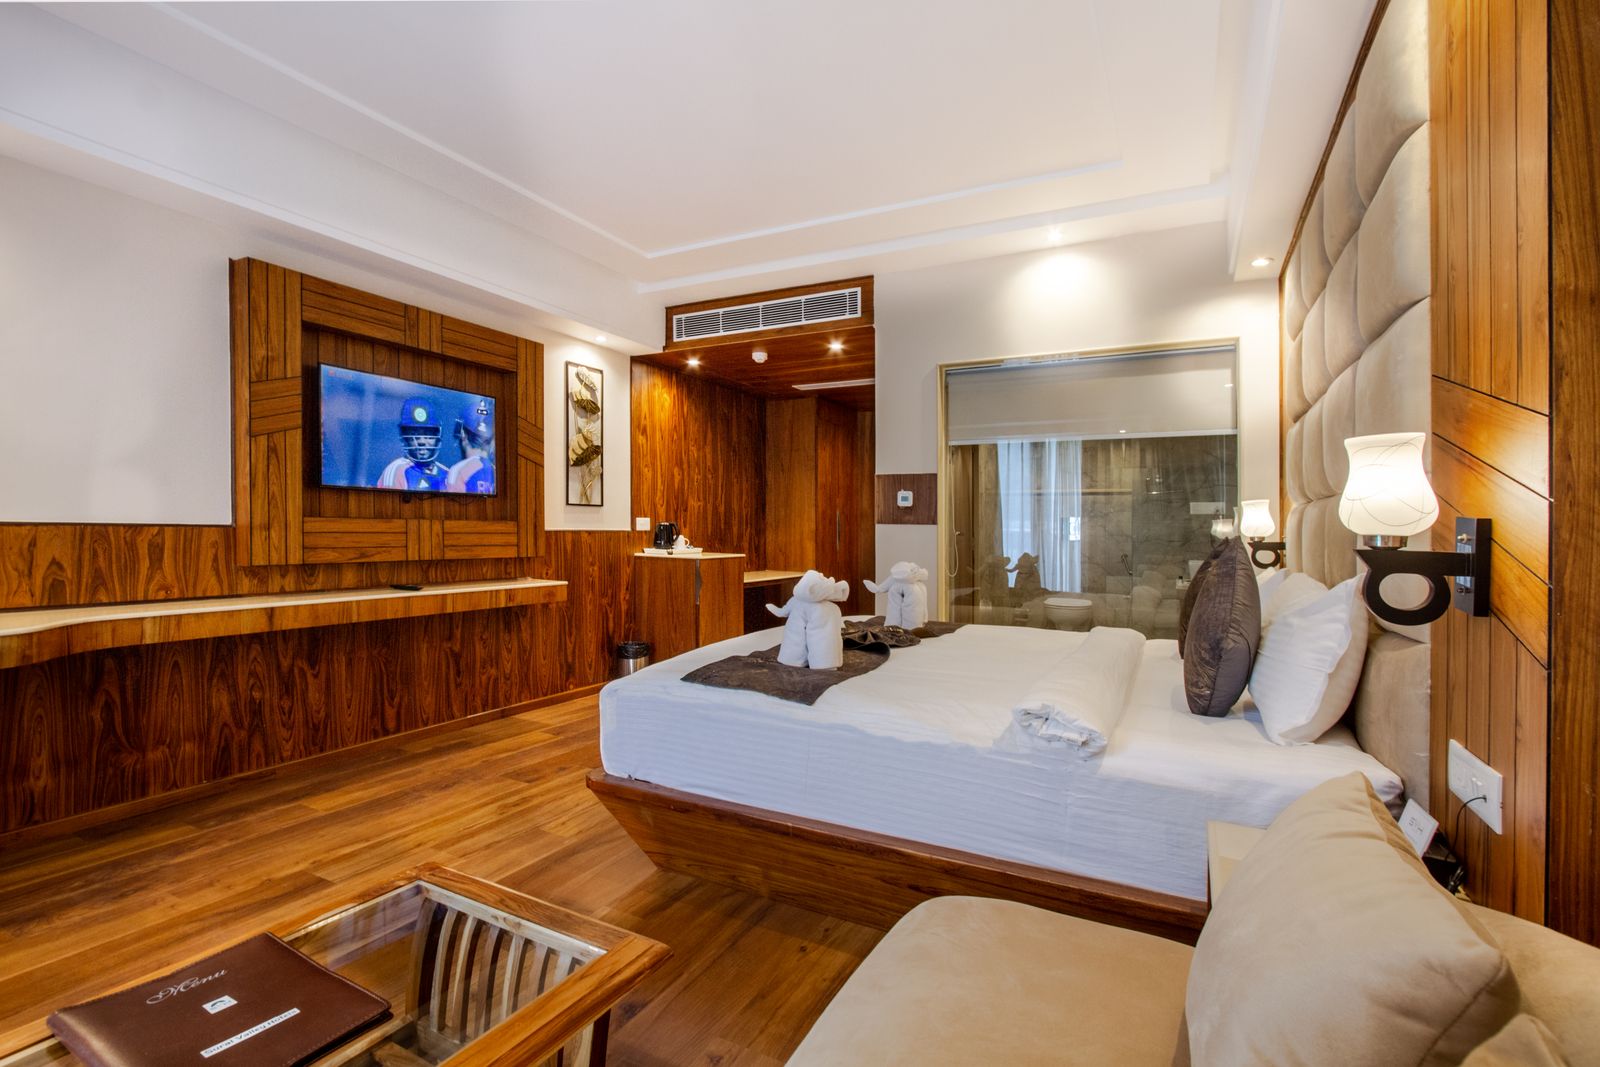
When a tired independent hotel becomes a Marriott or a Hilton, guests notice the new lobby, the new beds and the new sign.
Investors should notice something else: hotel PIP depreciation, the tax side of brand-required hotel renovations.
A PIP is not just a remodeling budget, my friends.
In the right hotel syndication, it can become a recurring engine of deductions for accredited investors.
In this post, I will show you what a PIP is, why it matters for your taxes, and where the traps are.
We will walk through a hypothetical 100-room conversion budget, line by line, with the typical tax treatment of each item.
And I will tell you why I never let a tax deduction drive an investment decision on its own.
What Is a Hotel Property Improvement Plan (PIP)?
A Property Improvement Plan, or PIP, is a list of upgrades a hotel brand requires before a property can fly its flag.
When a hotel converts to a brand like Marriott, Hilton, or IHG, or simply changes ownership, the brand typically issues a PIP.
A typical PIP touches nearly every part of the property:
- Guest room soft goods: carpet, drapes, bedding, wallcovering
- Case goods: beds, dressers, desks, nightstands, seating
- Guest bathrooms: vanities, tile, fixtures, lighting
- Lobby, breakfast area, and fitness room
- Exterior paint, signage, and parking areas
- Technology: TVs, Wi-Fi, door locks, property management systems
How often do hotel renovations happen?
Beyond the conversion PIP, hotels follow typical industry refresh cycles.
Soft goods are commonly refreshed every 5 to 7 years.
Case goods are commonly replaced every 10 to 12 years.
Brands also inspect regularly, and a tired property can receive a new PIP to keep its flag.
That rhythm is exactly why I call renovations a recurring deduction engine.
Why Does Hotel PIP Depreciation Matter for Your Taxes?
Most of a PIP budget is not spent on the building structure.
It is spent on furniture, finishes, fixtures, and equipment, and the tax code treats those very differently.
The building itself depreciates over 39 years, because hotels are nonresidential real property.
But the items a PIP replaces often fall into much shorter recovery periods.
Here are the three big levers:
- New FF&E is 5- or 7-year property. Furniture, carpet, TVs, and signage commonly qualify for bonus depreciation.
- Interior non-structural improvements may be qualified improvement property (QIP). QIP is 15-year property and bonus-eligible.
- Old components you rip out may be written off. Under the partial disposition rules, the remaining basis of retired items may be deductible.
The One Big Beautiful Bill Act, signed July 4, 2025, permanently restored 100% bonus depreciation.
It applies to qualified property acquired and placed in service after January 19, 2025.
So bonus-eligible PIP spending placed in service today could potentially be deducted in year one instead of over many years.
If you want the full background, read my guide to bonus depreciation for accredited investors.
The IRS rules on recovery periods are laid out in IRS Publication 946.
How Does a PIP Fit Vinney’s Hotel Conversion Strategy?
At Moneil Investment Group, our focus is simple.
We buy off-market, distressed, or foreclosed hotels, renovate them, and convert them to name brands.
Then we aim to exit in roughly 3 to 5 years.
The PIP is the heart of that business plan, and it works on two fronts at once.
First, it drives value.
A fresh, branded hotel can command higher RevPAR (revenue per available room) than a tired independent.
That is why hotel brands are partnering with syndicators to bring distressed properties back into their systems.
Second, it creates deductions.
The PIP adds a fresh layer of short-life assets on top of the cost segregation study done at acquisition.
Together, these can help create the large year-one paper losses that show up on investors’ K-1s.
“A renovation that serves the guest first will serve the investor second. Do it in that order, and the tax benefits follow.” — Vinney Chopra
Hotel PIP Depreciation Example: A Hypothetical 100-Room Conversion
Let me make this concrete with round numbers.
This is a hypothetical illustration only, not a real Moneil deal.
Imagine a 100-room hotel converting to a national brand with a $2.5 million PIP, about $25,000 per key.
| PIP Category | Hypothetical Budget | Typical Tax Treatment |
|---|---|---|
| Soft goods (carpet, drapes, bedding, wallcovering) | $400,000 | 5- or 7-year personal property; bonus-eligible |
| Case goods (beds, dressers, desks, seating) | $600,000 | 5- or 7-year FF&E; bonus-eligible |
| Guest bathrooms (vanities, tile, fixtures, lighting) | $650,000 | Often 15-year QIP; some items personal property; bonus-eligible |
| Lobby and public areas (finishes, furniture) | $350,000 | Furniture 5/7-year; interior finishes often 15-year QIP |
| Exterior and signage (signs, paving, facade) | $300,000 | Signage 5/7-year; paving 15-year; facade 39-year building |
| Technology (TVs, Wi-Fi, locks, systems) | $200,000 | 5-year personal property; bonus-eligible |
| Total | $2,500,000 | Majority commonly bonus-eligible |
Now suppose the facade and other structural work total about $400,000, and stay on the 39-year schedule.
That leaves roughly $2.1 million that could be bonus-eligible.
With 100% bonus depreciation, that $2.1 million could potentially be deducted in the year it is placed in service.
What could that mean for one investor?
Say you own 2% of the partnership as a limited partner.
Your share of a $2.1 million deduction would be $42,000.
If that loss offsets $42,000 of passive income at a 37% federal bracket, that is about $15,540 in federal tax.
Again, this is a hypothetical example, and results vary deal to deal.
Can Hotel PIP Depreciation Offset My W-2 Income?
This is the question I hear most, so let me be careful.
As a limited partner, you are generally a passive investor under IRC §469.
Passive losses generally offset passive income, such as income from other syndications, rentals, or gains when you sell passive investments.
They generally do not offset W-2 wages or active business income for a passive LP.
Unused passive losses carry forward indefinitely and are released when you fully dispose of the activity.
I explain how this works in detail in passive losses from hotel depreciation.
Talk to your CPA about how these rules apply to your own return before you invest.
Why You Should Never Overpay for a PIP Just for the Deductions
A deduction is not free money.
If you spend $1 to save 37 cents in tax, you are still out 63 cents.
The PIP must make economic sense on its own, through higher rates, higher occupancy, and a stronger exit value.
Watch for these warning signs:
- A PIP budget that is not supported by a realistic RevPAR lift
- A sponsor who sells the tax benefits harder than the business plan
- No contingency for construction delays or cost overruns
- No plan for depreciation recapture when the hotel sells
Remember, depreciation lowers your basis.
When the hotel sells, gain from personal property depreciation is generally taxed as ordinary income.
I cover that in depreciation recapture: how to minimize the sting.
And before you invest, learn how to know if a hotel deal is underwritten properly.
How Does Hotel Renovation Depreciation Become a Recurring Engine?
Most of our hotels are held for about 3 to 5 years.
So the investor usually enjoys the big conversion PIP, not every future refresh cycle.
The recurring part comes from reinvesting.
When one hotel sells, many investors roll their capital into the next conversion.
That next hotel brings a new cost segregation study, a new PIP, and a fresh round of short-life assets.
Done wisely, each new deal can help offset passive gains from the last one.
To see the big picture, start with why hotels are the best real estate tax shelter.
And to understand why timing matters so much now, read why 100% bonus depreciation is back and hotel investors stand to win.
Frequently Asked Questions
What is hotel PIP depreciation?
It is the tax depreciation on the upgrades a brand requires in a Property Improvement Plan.
Much of that spending, like furniture, carpet, and technology, often qualifies for shorter lives and bonus depreciation.
Is all PIP spending eligible for bonus depreciation?
No. Structural work, such as roofs, facades, and enlargements, stays on the 39-year building schedule.
Elevators and internal structural framework are also excluded from qualified improvement property.
Can I deduct the old furniture and fixtures that were removed?
Possibly. Under the partial disposition rules, the remaining tax basis of retired components may be written off.
This depends on how assets were recorded, so your CPA and cost segregation provider should guide it.
Do I need to be an accredited investor to invest in these hotel deals?
Yes. Our offerings are made under Reg D Rule 506(c) to verified accredited investors only.
You can review the SEC accredited investor definition to see if you qualify.
Key Takeaways
- A PIP is a brand-required upgrade plan issued at conversion, reflag, or change of ownership.
- Hotel PIP depreciation can turn much of a renovation budget into 5-, 7-, and 15-year bonus-eligible property.
- Removed components may produce additional write-offs under the partial disposition rules.
- The PIP drives value through higher RevPAR and brand power, and creates deductions at the same time.
- For passive LPs, these losses generally offset passive income, not W-2 wages.
- Never invest in a renovation just for the tax deduction; the business plan must stand on its own.
I have raised $250M+ across 36 full-cycle deals, and every great one started with a conversation.
If you want to see how a conversion PIP could fit your own tax-efficient investing plan, let’s talk.
Book your free strategy call with Vinney
And join our Mastermind Family, where we learn, grow, and invest together.
God bless you. Smile and Succeed. 🙏😊
Disclaimer: This article is for educational and informational purposes only and does not constitute tax, legal, or investment advice. Tax outcomes depend on your individual situation and the terms of each offering. Consult your CPA and legal advisors before making investment decisions. Offerings are available to accredited investors only. Past performance is not indicative of future results.
About the Author: Vinney Chopra is the founder and CEO of Moneil Investment Group and a 5x Amazon bestselling author. He arrived in America with $7 in his pocket and has since raised $250M+ across 36 full-cycle deals, helping accredited investors invest in hotel syndications. Learn more at AccreditedInvestor.blog or book a free strategy call.